Free · 30 seconds · The Retirement Income Roadmap

Bills paid from income, whether or not you keep working.

A big balance can still leave you uneasy about the day the paycheck stops. I think that's because every bill would come out of it. Income that shows up every month is what actually makes work a choice. Answer seven questions and you'll see how far you are from that, and what it would cost to get there.

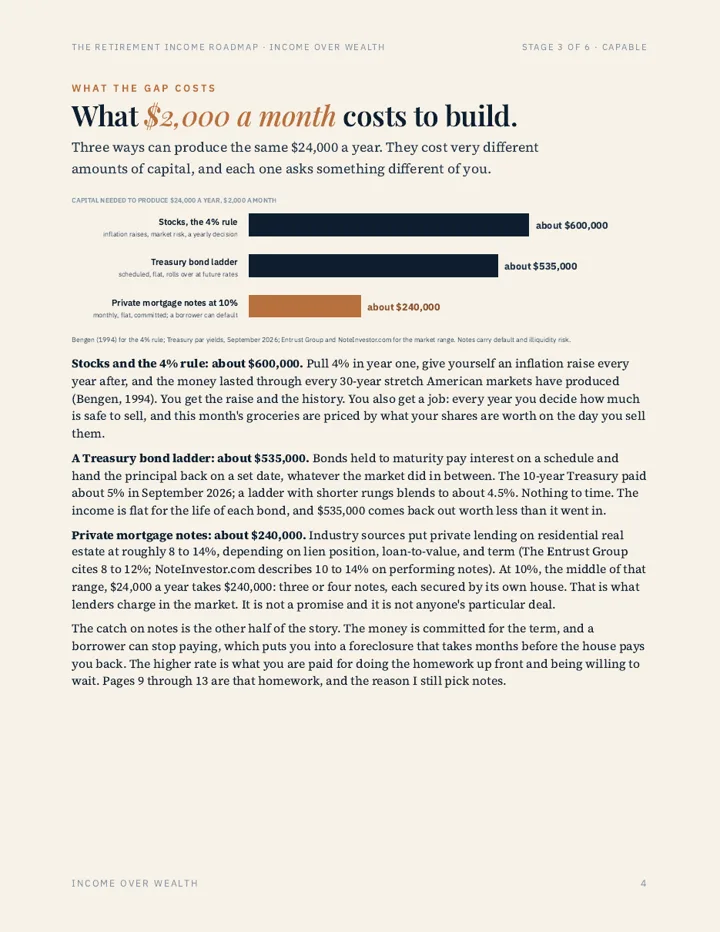
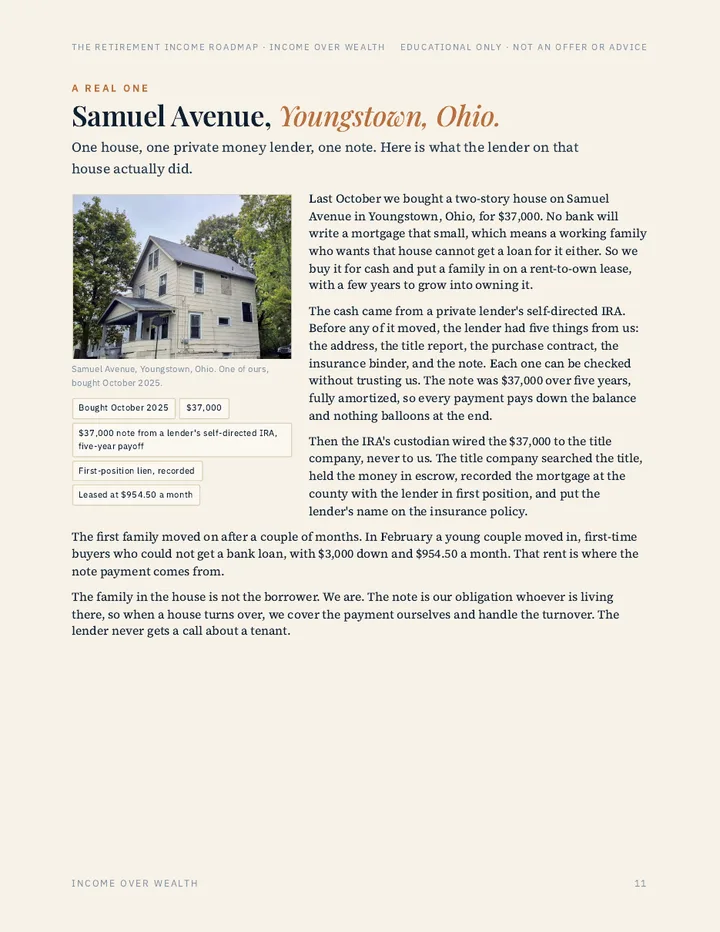
Roadmap cover page Roadmap page: what a $2,000 a month gap costs to build Roadmap page: the Samuel Avenue house

Your Roadmap is 17 pages built from your answers, and it lands in your inbox in about a minute. It uses ranges, never exact dollars, and nothing you type gets shared.

Dan WilsonDan WilsonReal estate investor and private lender
The Math

What a $2,000 gap costs to fill.

Say you want $2,000 a month of your bills covered by income, whether you keep working or not. That's $24,000 a year your savings have to produce, every single year. There are three ways to do it. They cost very different amounts of money, and each one asks something different of you.

Stocks and the 4% rule

$600,000

You pull 4% in year one, then give yourself a raise for inflation every year after. It's lasted through every 30-year stretch American markets have produced, which is why people like it. The catch is that every year you're deciding how much is safe to sell, and this month's groceries get priced by whatever your shares are worth the day you sell them.

A Treasury bond ladder

$535,000

Bonds you hold to maturity pay interest on a schedule and hand your money back on a set date, no matter what the market did in between. There's nothing to time. The trade-off is that the income stays flat for the life of each bond, and the $535,000 comes back out worth less than it went in.

Private mortgage notes

$240,000

Private lenders on residential real estate commonly charge 8 to 14%, depending on lien position, loan-to-value, and term (The Entrust Group, NoteInvestor.com). At 10%, roughly the middle of that range, $24,000 a year takes $240,000. That's three or four notes, each secured by its own house. To be clear, that's the market rate, not anyone's particular deal. And like every investment it carries risk: the money is committed for the term, and if a borrower stops paying, getting it back takes time.

Your Roadmap does this same math with your own gap. It also gives selling shares, dividends, rentals, annuities, and reverse mortgages a fair hearing, and shows you how far along you already are. Price my gap →

Being the Bank

A payment every month, from a house you never manage.

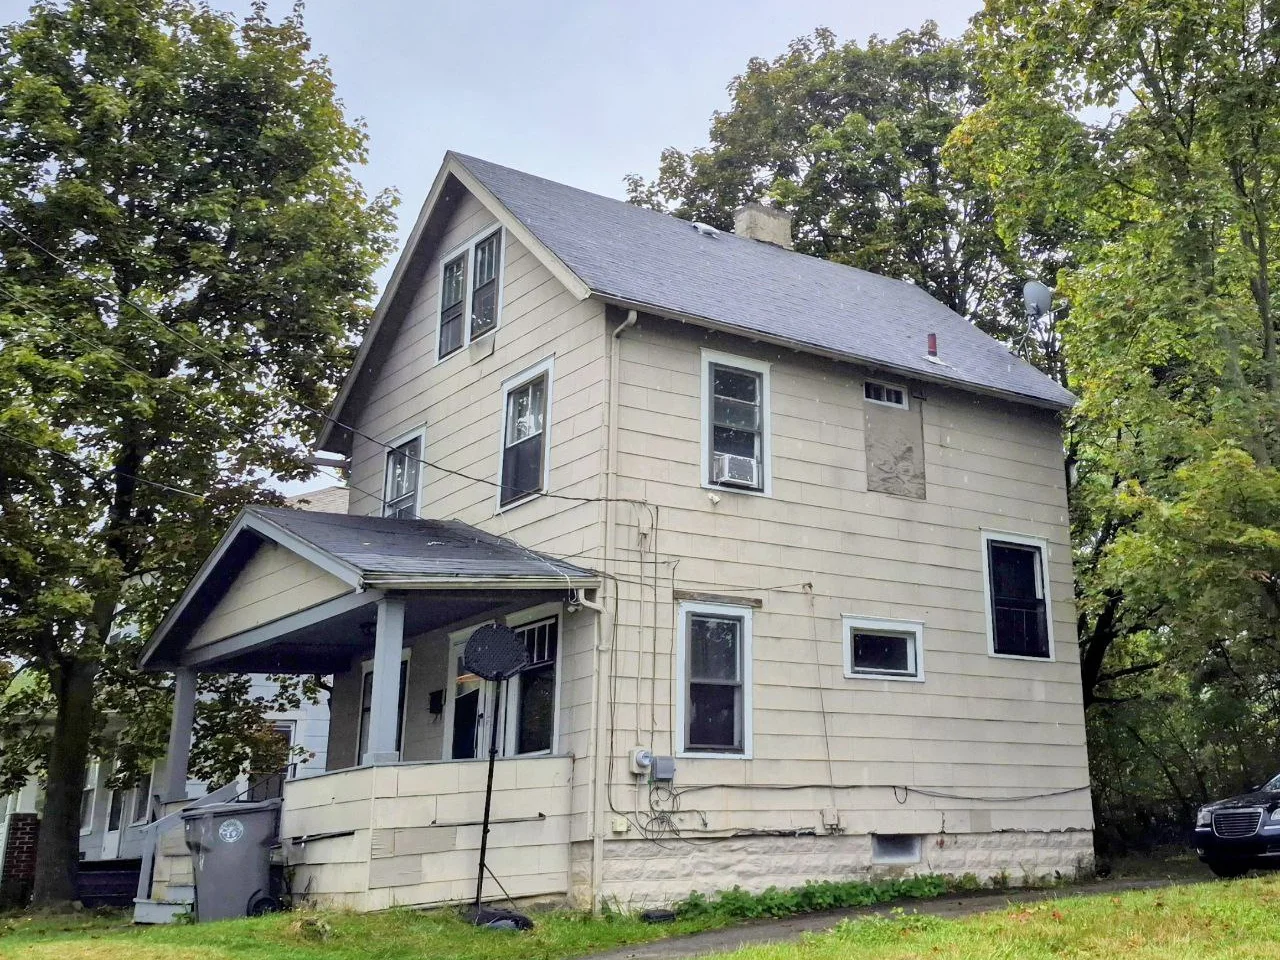
The two-story house on Samuel Avenue in Youngstown, Ohio
Samuel Avenue, Youngstown, Ohio. One of ours.

Here's how we set up our houses. They're for families who want to be owners instead of tenants. They can afford the payment, but no bank will write a mortgage on a $37,000 house. So we buy it and give them a rent-to-own lease with a real path to buying it. Someone who's working toward owning a place tends to look after it like it's already theirs.

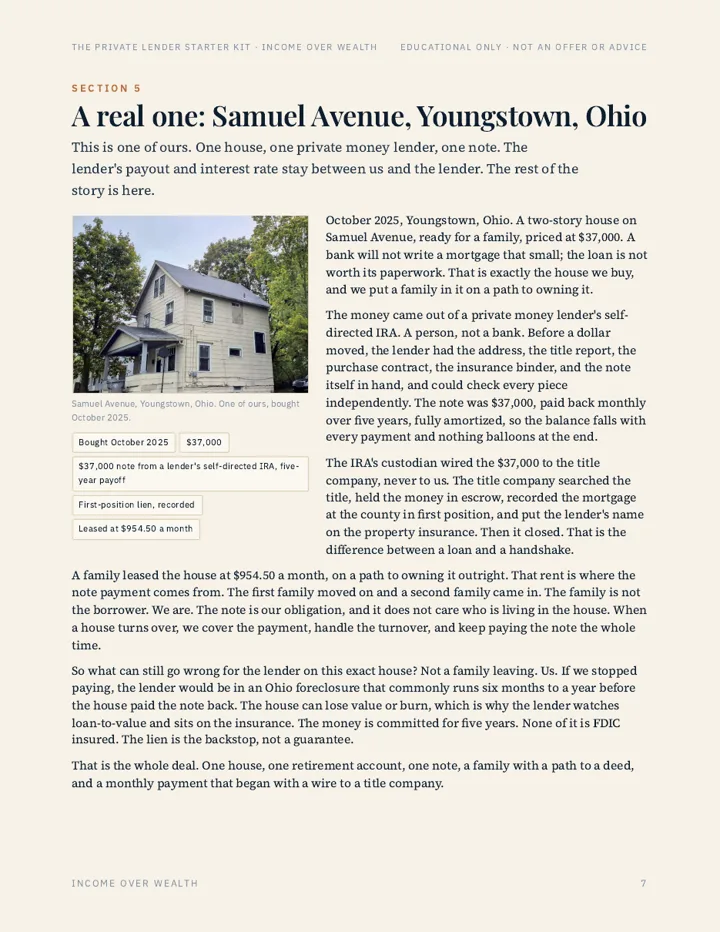
Samuel Avenue in Youngstown is one of them. We bought it in October 2025 for $37,000, with money from one person's self-directed IRA: a $37,000 note in first position, five years, fully amortized. The first family moved on after about ten weeks. Then in February a young couple moved in, first-time buyers who couldn't get a bank loan, and put $3,000 down toward owning it.

Worth pointing out: the family isn't the borrower. We are, no matter who lives in the house, so the lender never gets a call about a tenant. I own rentals too, and as the landlord I'm the one taking the repair calls and finding the next family when one moves out. With a note, the owner and the family living there take care of the house. The lender's part is the note.

I walk through the whole deal, page by page, in the Starter Kit.
On paper

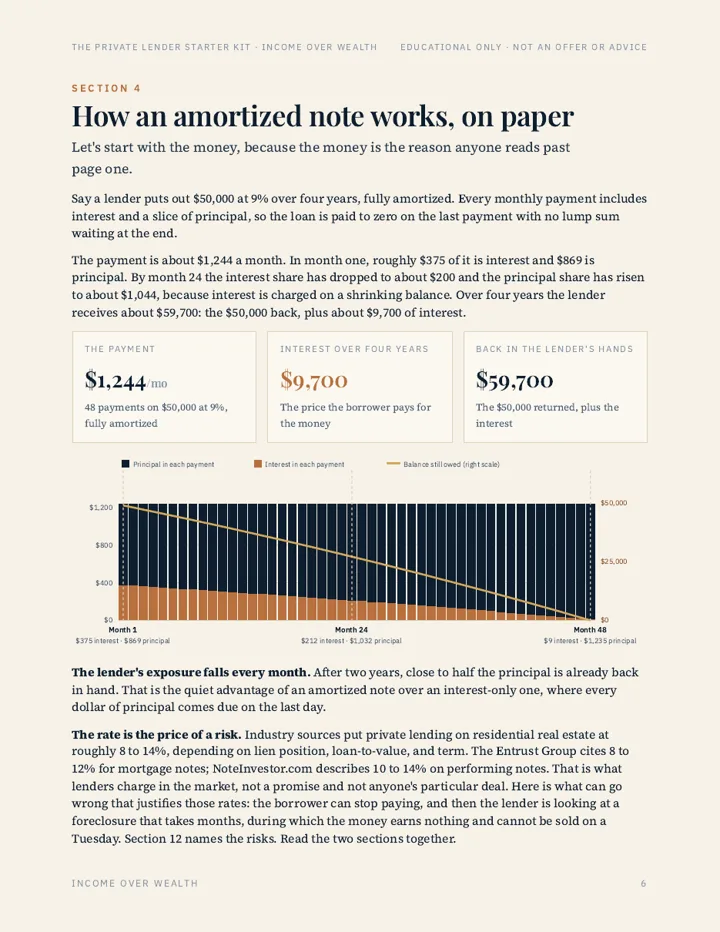
Say a lender puts out $50,000 at 9% over four years. About $1,244 shows up every month, part interest and part principal, and the balance hits zero at month 48. The lender never fixes a furnace, never finds a tenant, and never has to sell a share to pay a bill. The trade is that the money's committed for four years, and if the borrower stops paying, the house pays you back after a wait, through the recorded lien.

See the whole deal in the Starter Kit →

$0$400$800$1,200 $50,000$25,000$0 Month 1$375 interest · $869 principalMonth 24$212 interest · $1,032 principalMonth 48$9 interest · $1,235 principal Principal in each payment Interest in each payment Balance still owed (right scale)
Starter Kit page: how an amortized note works, on paper Starter Kit cover Starter Kit page: a real one, Samuel Avenue
The Private Lender Starter Kit

Be the bank on a house, without owning the house.

It's one free PDF, 23 pages, about the income side of real estate without the landlording. Basically, how being the bank works from the lender's side, so you can judge any loan yourself.

  • $3,000 a month of your bills, paid three different ways, with the catch on each.
  • What being the bank pays: a $50,000 note at 9%, charted month by month.
  • Two real ones, Samuel Avenue and Silsby Road. The houses, the lender's wire, the families, and what can still go wrong.
  • The IRA path, with eight custodians compared side by side.
  • The ten-question due-diligence checklist on one printable page, so you can put any borrower on the spot. Me included.

Like every investment, a private note carries risk. The kit covers what can go wrong and who this isn't for, so you can decide with your eyes open.

Send Me the Starter Kit

Free. One PDF. No spam, unsubscribe anytime.

Who's Writing
Dan Wilson

Dan Wilson

  • 14 years in the Air Force
  • 100+ real estate deals
  • 24 rentals in Ohio

Both sides of the note

Quick background: I spent 14 years in the Air Force, I've done 100+ real estate deals, and I hold 24 rentals in Ohio. I fund houses with private money, and I lend private money myself. So everything here is written from both sides of the note.

The Samuel Avenue house above is one of mine. The lender on it is a real person with a retirement account. And the checklist in the kit is the one I'd want any borrower to answer, me included.

More about me →

The Private Lender Fit Call · Free · 30 minutes · I call you

Leave the call knowing exactly how you'd make your first private loan, or why you shouldn't.

If you want to learn what it takes to be a private lender and figure out whether it fits your situation, apply for a Private Lender Fit Call. It's a conversation, not a pitch. It's thirty minutes on the phone about your money and your situation. By the end you'll have a clear read on fit and an answer to your one question, and you'll get your next step in writing within a day.

Book My Fit Call

Free. Three short questions, then pick a time.

Watch or Listen

New videos every Tuesday and Saturday.

Plain-English breakdowns of retirement income. Where monthly income actually comes from, what a gap costs to fill, and the real numbers from the houses we buy. Every video is also a podcast episode, and most run about fifteen minutes.

Or, the Short Version

Skip the check, get the letter instead.

One email every Tuesday morning, mostly about what happened in the business that week and what it means for your income. No pitches, and you can leave whenever you want.