Foreclosure Timelines by State
How long a lender waits, from the first missed payment to the sale, is set by the state the house sits in. Same missed payment, wildly different wait. This is why question 7 on the due-diligence checklist asks about the state before it asks about the rate.
 Dan WilsonReal estate investor and private lender
Average time in foreclosure for homes foreclosed in the second quarter of 2026, the lowest since 2013. Down 13% from a year earlier. Source: ATTOM.
Longest and shortest average waits, Q2 2026
ATTOM's averages count foreclosures completed in the quarter, so they include old, tangled cases. A clean private note with the paperwork in order will usually move faster than the state average. The spread between states is the lesson.
Courts or a trustee
Every state falls into one of two camps. Federal rules keep a lender from starting either process until the borrower is at least 120 days behind.
Through the courts
20 states, and the usual route in two more
- The lender files a lawsuit.
- The borrower is served and can answer.
- A court enters a judgment.
- Only then is the house sold.
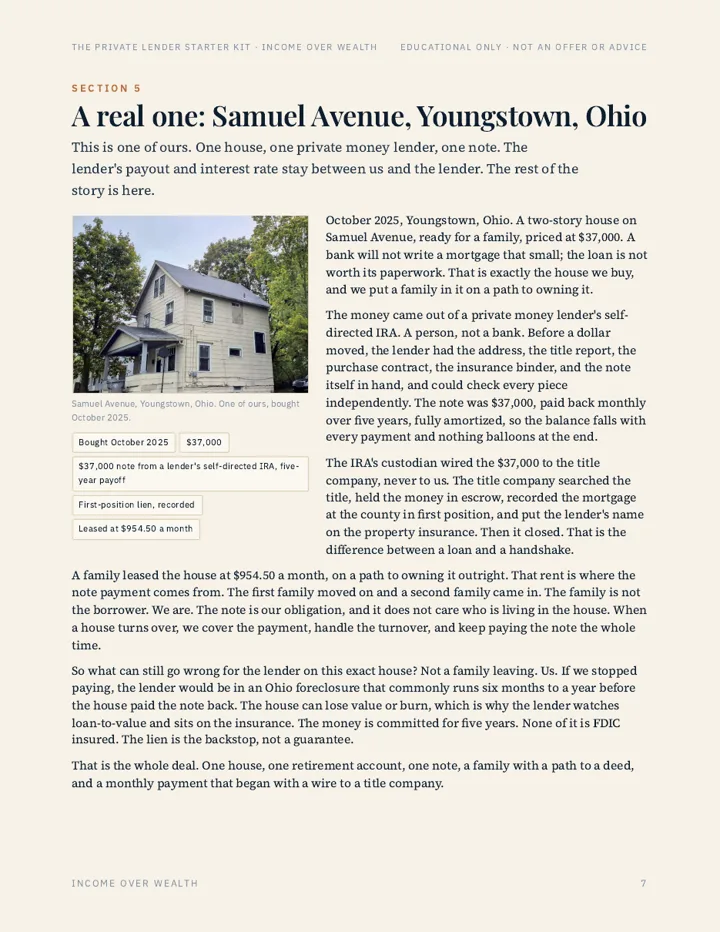
Months to years. Ohio, where our houses are, is a judicial state; in my experience a clean Ohio foreclosure commonly runs six months to a year.
Trustee sale
29 states, no court involved
- The loan document is a deed of trust with a power-of-sale clause.
- A trustee records a notice of default.
- Then a notice of sale.
- The trustee holds the auction.
Usually months.
Which process each state uses
- AlabamaNonjudicial
- AlaskaNonjudicial199
- ArizonaNonjudicial
- ArkansasNonjudicial
- CaliforniaNonjudicial
- Colorado2Nonjudicial
- ConnecticutJudicial1,626
- DelawareJudicial
- District of Columbia3Both
- FloridaJudicial
- GeorgiaNonjudicial
- Hawaii4Both2,293
- IdahoNonjudicial
- IllinoisJudicial
- IndianaJudicial
- IowaJudicial
- KansasJudicial
- KentuckyJudicial
- LouisianaJudicial3,491
- MaineJudicial
- Maryland2Nonjudicial
- MassachusettsNonjudicial
- MichiganNonjudicial
- MinnesotaNonjudicial
- MississippiNonjudicial
- MissouriNonjudicial
- MontanaNonjudicial
- NebraskaNonjudicial
- NevadaNonjudicial1,507
- New HampshireNonjudicial157
- New JerseyJudicial
- New Mexico1Judicial
- New YorkJudicial2,007
- North CarolinaNonjudicial
- North DakotaJudicial
- OhioJudicial
- OklahomaJudicial
- OregonNonjudicial
- PennsylvaniaJudicial
- Rhode IslandNonjudicial
- South CarolinaJudicial
- South DakotaNonjudicial
- TennesseeNonjudicial
- TexasNonjudicial155
- UtahNonjudicial
- VermontJudicial
- VirginiaNonjudicial
- WashingtonNonjudicial
- West VirginiaNonjudicial196
- WisconsinJudicial
- WyomingNonjudicial173
1 Judicial in most cases; a nonjudicial process exists for some post-2006 loans. 2 Nonjudicial with some court supervision. 3 Judicial, sometimes nonjudicial. 4 Nolo lists Hawaii under both; judicial is also common. Process by state: Nolo, "Chart: Judicial vs. Nonjudicial Foreclosures," updated May 7, 2026. Days: ATTOM, Mid-Year 2026 U.S. Foreclosure Market Report, July 16, 2026, which publishes the five longest and five shortest state averages for homes foreclosed in the second quarter. Laws change and vary within a state; confirm the process where the property sits before you lend.
What the state decides for you
Like every investment, a private note carries risk, and the state decides what the risk costs in time. If a borrower stops paying, the lender's recorded lien is what gets the money back, and in a judicial state that runs through a courtroom. Most missed payments are late, not lost, and the cure period in the loan documents exists for that reason.
Before closing, know two things. What day 31 looks like in that state, and whether money that might be needed back soon belongs in a note there at all.
The Private Lender Starter Kit
Free, 23 pages: what happens when a payment is missed, step by step, the four documents, lien position and the cushion, and the ten questions to ask any borrower before a dollar moves.
Send Me the Starter Kit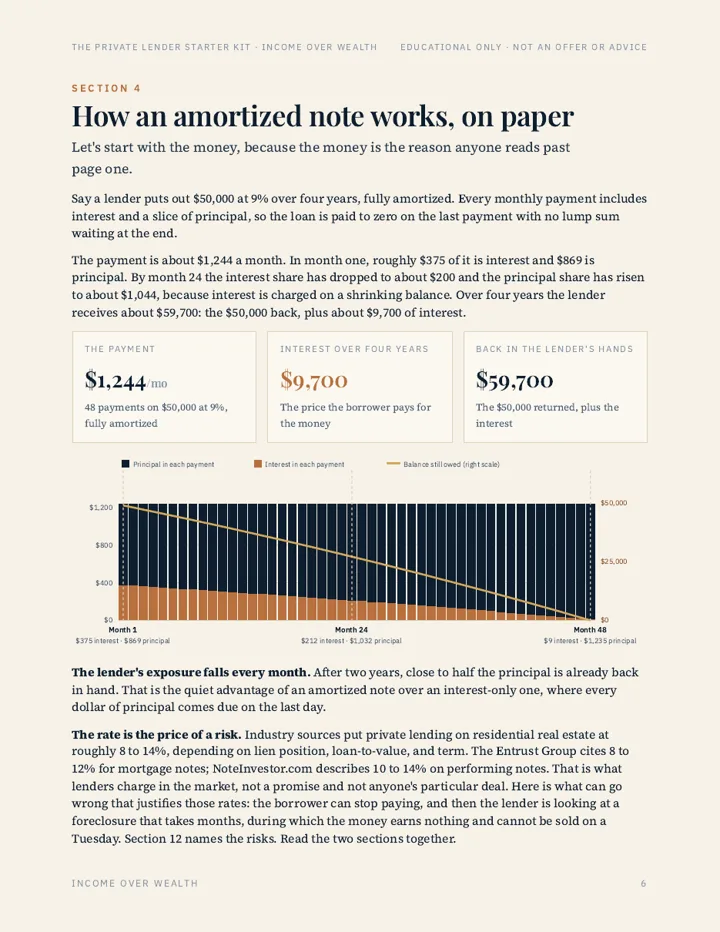
Educational content only. Nothing here is an offer to sell or a solicitation of an offer to buy any security, loan, or investment, and nothing here is legal, tax, or investment advice. Any examples are hypothetical and for illustration only. Consult your own advisors before making any financial decision.